Social Security Disability Benefits:

How Much Does Disability Pay? SSDI and SSI Payment Amounts Explained

What You Receive and How They Work
A woman resting on her sofa at home, looking out of the window

How much disability actually pays depends on which program you qualify for. SSDI (Social Security Disability Insurance) payments are based on your own earnings history and can reach several thousand dollars a month for higher earners. SSI (Supplemental Security Income) is a flat federal base rate for those with limited income and resources, sometimes topped up by a state supplement. This guide breaks down how each is calculated, what the current maximum and average payments generally are, and clears up a common misconception: whether moving to a different state can actually get you a bigger check.

How Much Does Disability Pay?

Anyia, Representative

"Disability pay depends on which program you're on: SSDI amounts vary widely based on your individual earnings history, while SSI pays a flat federal base rate that may be topped up by a state supplement. Neither program pays a single, uniform amount to every claimant, but the reasons the amount varies are completely different between the two.

This distinction is the foundation for everything else on this page, and it's worth keeping in mind throughout: SSDI and SSI aren't just two names for the same benefit calculated slightly differently. They're structurally different programs, one earnings-based, one need-based, and that difference is what explains almost everything covered in the rest of this guide, including a common misconception about moving states for a bigger check, addressed directly later on.

If you're not sure which program applies to your situation, or whether both might, that's worth sorting out before trying to estimate an amount, since the calculation methods are entirely different between the two. Some claimants qualify for both programs at once, in which case both calculation methods apply together, covered in the FAQ later on this page."

Anyia – Representative

How SSDI Payments Are Calculated

Your SSDI payment is based on your average indexed monthly earnings over your working years, run through a formula Social Security calls your Primary Insurance Amount (PIA); it is not a flat, one-size-fits-all amount and does not depend on your state.

It covers:

Average Indexed Monthly Earnings

Your Average Indexed Monthly Earnings (AIME) reflects your earnings history over roughly your 35 highest-earning years, adjusted ("indexed") to account for changes in average wages over time. This means your SSDI payment is genuinely personal to your own work history, not a category or bracket you fall into, and no two claimants with different earnings histories will have exactly the same payment amount, even if their conditions and approval dates are similar. Your work credits establish whether you're eligible for SSDI at all; your AIME determines how much you receive once you are.
The Primary Insurance Amount (PIA) Formula

Your AIME is then run through a formula that converts it into your Primary Insurance Amount (PIA), the actual monthly benefit figure. This formula is progressive by design, meaning it replaces a larger percentage of earnings for lower earners than for higher earners, which is part of why two claimants with different earnings histories can have SSDI amounts that don't scale up in a simple, linear way. A claimant who earned twice as much over their career generally does not receive twice the SSDI payment, since the formula is intentionally weighted to replace a larger share of income for lower earners.


What Is the Maximum and Average SSDI Payment?

SSDI payment amounts vary by individual, but Social Security publishes a maximum monthly benefit figure and a national average that update most years. The current maximum monthly SSDI payment is $4,152, and the average is $1,635.


These figures adjust periodically through cost-of-living adjustments (COLA), which is part of why a number that was accurate a year or two ago can already be outdated. The most reliable way to know your own likely amount is checking your personal Social Security statement directly, rather than relying on a general published average, since your own AIME and PIA are specific to your individual earnings history.


It's also worth understanding what these headline figures actually represent: the maximum reflects the highest possible payment for someone with a long history of maximum taxable earnings, which relatively few claimants actually reach, while the average reflects the full range of claimants nationally, including many with more modest earnings histories. Neither figure is a good predictor of your own specific amount, which is exactly why checking your own record directly matters more than either headline number.


3D illustration of a clipboard with checkboxes and a pen

How Much Does SSI Pay?

Elizabeth, Senior Representative

"SSI pays a flat federal base rate to eligible individuals, reduced by any countable income you have, and some states add a supplemental payment on top of the federal amount. The SSI maximum monthly payment is $994 for an individual and $1,491 for a couple.

Unlike SSDI, SSI doesn't scale up based on a work history at all, since it's structured around financial need rather than earnings. The federal base rate is the starting point, and your actual monthly payment can be reduced below that base rate depending on other countable income you have. This is a meaningfully different structure than SSDI's earnings-based calculation, and it's worth keeping the two mental models separate rather than assuming SSI works the same way SSDI does, just with different numbers. The state-supplement piece mentioned above is covered in more detail in the next section.

Based in Durham. Serving all of North Carolina. Start your free case review or call (888) 251-5551. No upfront cost."

Elizabeth – Senior Representative

Does Your Payment Amount Vary by State?I

SSDI does not vary by state. The same federal formula applies everywhere, based entirely on your own earnings history. SSI can vary somewhat by state, but only because some states add an optional State Supplemental Payment (SSP) on top of the federal base rate. Moving to a different state won't change your SSDI amount, and it will only change your SSI amount if the two states have different SSP policies.

It isn't. SSDI's calculation is identical nationwide, since it's based entirely on your individual earnings record, not where you happen to live. SSI is the one place where genuine state variation exists, and even there, it's specifically because some states choose to add an optional State Supplemental Payment on top of the federal base rate, administered either by the state itself or, in some states, by SSA on the state's behalf. A claimant considering a move for reasons unrelated to benefits shouldn't expect their SSDI amount to change at all, and should check the specific SSP policy of any state they're considering if SSI is part of their situation, rather than assuming benefits generally follow a "better states pay more" pattern. This is worth clearing up plainly rather than glossing over, since a claimant making a major life decision, like relocating, based on a mistaken belief about how disability pay works could end up disappointed for reasons that had nothing to do with their actual eligibility or amount.

Can Other Benefits Reduce Your SSDI Payment?

Some benefits can reduce your SSDI payment, most notably workers' compensation and certain other public disability benefits, while most private disability insurance and most pensions do not affect your SSDI amount.

This distinction matters for financial planning and is worth understanding clearly rather than guessing. Workers' compensation and certain other public disability benefits can trigger an offset that reduces your SSDI payment, generally so that the combined total doesn't exceed a certain percentage of your prior earnings. Most private disability insurance policies, purchased individually or through an employer, generally do not affect your SSDI amount at all, nor do most pensions. If you're receiving, or expect to receive, workers' compensation or another public disability benefit alongside SSDI, understanding how the offset applies to your specific situation is worth doing before you're surprised by a reduced payment. It's also worth being clear about what doesn't count here: private long-term disability insurance you or an employer purchased, and most pension income, are generally treated as entirely separate from SSDI and don't trigger this kind of offset.

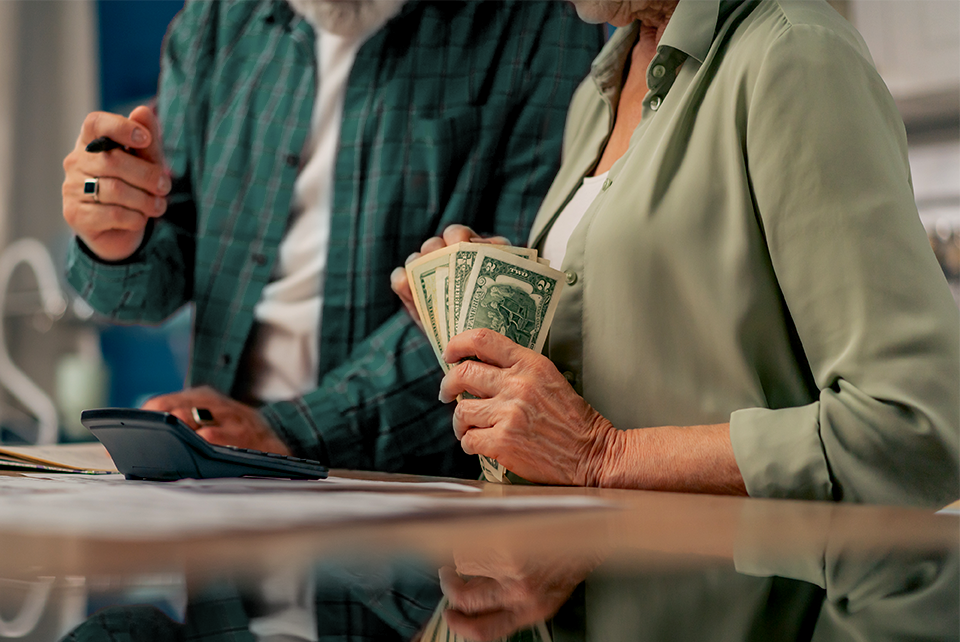
An older couple at their kitchen table counting cash beside a calculator

Will Your Payment Change at Retirement Age?

Your SSDI payment does not decrease at full retirement age. It simply converts to a Social Security retirement benefit at the same amount you were already receiving.

This is worth stating clearly and directly, since it's a genuine, common financial-planning worry for claimants approaching retirement age while on SSDI, and the honest answer is reassuring: there's no cliff, no reduction, and no separate application required to make this happen. Your benefit simply continues, now classified as a retirement benefit rather than a disability benefit, at the same dollar amount you were already receiving. For a claimant already budgeting carefully around a fixed monthly amount, knowing this transition happens automatically and without a change in amount can meaningfully ease one part of an otherwise uncertain financial picture.

Form Image
North Carolina city skyline

Talk to Our Team About Your Disability Payment

Payment amount depends on program type and your individual earnings history, not your location, and understanding how the calculation actually works helps set realistic expectations rather than relying on a general average that may not reflect your own situation. Whether your concern is estimating what to expect, understanding an offset, or planning around the transition to retirement age, getting a clear, accurate picture is worth doing early rather than guessing.

Want help understanding what you might be owed? Start your free case review, or talk to our team directly.

  • $0 Upfront Fees

  • No Fees Unless You Win

  • Serving Clients in All 50 States

  • Thousands of Disability Claimants Served

Get your free case review:

(888) 251-5551

No upfront cost. You only pay if your claim is approved.

Common questions about Disability Payment Amount

It can be partially taxable depending on your total household income; SSI is generally not taxable, since SSI is a needs-based benefit rather than earned income.

Yes, in some cases (concurrent benefits), typically when your SSDI amount is low enough that you still qualify financially for SSI. When this happens, both calculation methods apply together, your SSDI amount based on earnings, topped up by an SSI amount based on remaining financial need.

In some cases, certain family members may qualify for auxiliary benefits based on your work record, a spouse, children, or in some cases a disabled adult child, though this varies by situation. disability benefits for dependents.

Yes, SSDI amounts are adjusted periodically for cost-of-living increases (COLA), the same as retirement benefits, which is the same mechanism that periodically shifts the maximum and average figures discussed earlier on this page.

No. SSDI is based entirely on your earnings record and is the same regardless of which state you live in. SSI is the only program where state matters at all, and only because of optional state supplements, covered in detail earlier on this page.

Ready to talk to a
disability advocate?

This page is the starting map. Every stage above links to a deeper guide when you need it, and if you're ready to have someone work your claim with you, our team is here.

Based in North Carolina. Serving clients nationwide. Start your free case review or call us. No upfront cost. You only pay if you win.

START A FREE CASE EVALUATION
1/7

Are you currently receiving Social Security Disability Benefits?

← Go Back

Are you currently seeing a medical provider regularly?

← Go Back

Are you currently represented by a disability attorney or advocate?

← Go Back

Is your current age between 50 and 62?

← Go Back

Are you currently out of work?

← Go Back

Have you worked 5 out of the last 10 years?

← Go Back

Confetti

Great news! Based on your answers, you may be eligible for Social Security disability benefits. Complete the form below for your FREE case evaluation.

Select State
Please select a state.

This website is an advertisement. Clauson Disability is a national advocacy organization and is not a law firm. Clauson Disability is a private organization and is not affiliated with, endorsed by, or connected to the Social Security Administration (SSA) or any other government agency. We provide non-attorney disability advocacy and support services and do not provide legal advice, legal services, or legal representation. Contacting us, submitting a form, or speaking with our team does not create a representative-client relationship. By providing your contact information, you agree to our Terms & Conditions and Privacy Policy and consent to receive communications from us by phone, text message, and/or email, including through automated technology where permitted. Consent is not required as a condition of service. We do not determine eligibility or qualify any applicant for Social Security Disability Insurance (SSDI) or Supplemental Security Income (SSI). Only the SSA determines eligibility and benefit amounts. SSDI benefits vary based on work history, medical eligibility, and other factors. $4,152 represents the maximum monthly SSDI benefit; actual amounts vary based on individual circumstances.

Contact Us Call Now